Sensex Surges 900 Points as Reliance Ignites Rally, Oil Cools and FIIs Return
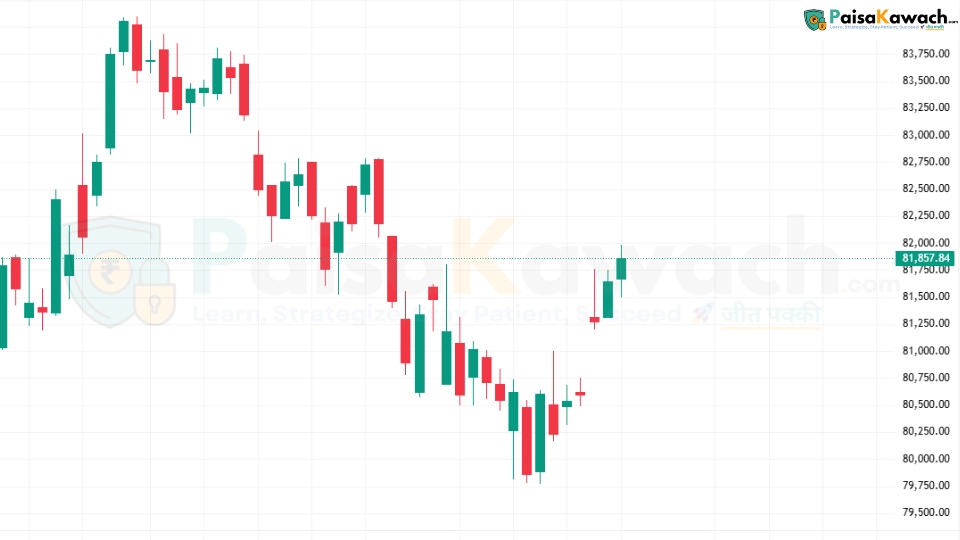
Indian equities opened the new month with a powerful surge on Monday, November 2, 2026, as a confluence of positive catalysts drove the benchmark indices to their third consecutive session of gains. The Sensex jumped over 900 points in early trade to cross 75,400, while the Nifty 50 reclaimed 23,300, gaining over 1.2%.
The rally was led by Reliance Industries, which surged over 6% after reporting a record quarterly profit, while cooling crude oil prices and returning foreign institutional investor flows provided the broader market with its strongest tailwind in weeks.
Reliance Ignites the Rally with Record Q2 Profit
The day's dominant story was Reliance Industries, India's most valuable company, which reported a 33.8% year-on-year jump in consolidated net profit to ₹29,550 crore for the September quarter, its highest ever. Consolidated revenue rose 27.8% to ₹3.62 lakh crore, while EBITDA climbed 23.9% to a record ₹62,409 crore.
Why the oil-to-chemicals business delivered
The star performer was Reliance's oil-to-chemicals (O2C) segment, which benefited from a surge in global fuel margins amid supply disruptions. Jefferies noted that consolidated EBITDA beat its estimates by 6%, driven entirely by O2C strength, with the segment's EBITDA jumping 48% quarter-on-quarter to ₹25,200 crore. The brokerage raised its FY27 and FY28 EBITDA estimates by 6% and 2% respectively, maintaining a buy rating with a target price of ₹1,710.
JPMorgan maintained its overweight rating and raised its target to ₹1,675 from ₹1,625, citing the O2C beat and expecting strong refining margins through the winter. Kotak maintained buy with a ₹1,500 target, highlighting that retail recovery depends on festive demand and returns from digital commerce investments.
The one soft spot was retail, where EBITDA missed estimates by 6% as investments in quick commerce and inflation weighed on margins. But the market chose to focus on the O2C beat and the telecom growth, sending the stock to an intraday high of ₹1,244 before it settled near ₹1,230.
- Record profit of ₹29,550 crore: Up 33.8% year-on-year, driven by O2C margins and telecom growth.
- O2C EBITDA up 48% QoQ: Global fuel margin surge delivered the beat, with Jefferies raising estimates and maintaining a ₹1,710 target.
- Retail miss: Quick-commerce investments and inflation squeezed margins, but the market looked past it.
Oil Cools Below $111 on Iran Diplomacy Hopes
The second major driver of Monday's rally was a sharp decline in crude oil prices. Brent crude fell 2.7% to $110.37 per barrel, while WTI dropped below $102, as Iranian negotiators remained in Doha for a third consecutive day of talks with Qatari mediators on a proposal to reopen the Strait of Hormuz within two days of a deal with Washington.
Why this matters more than any earnings beat
For weeks, elevated crude has been the single biggest overhang on Indian markets, pressuring the rupee, inflation expectations, and corporate margins. Brent had surged 13.6% in October, touching $118 last week on fears of a US strike on Iran. Monday's pullback, driven by genuine diplomatic progress rather than technical correction, offered the market its first real relief on this front in weeks.
The rupee opened stronger at 94.8850 per dollar, up marginally from Friday's close of 94.95, helped by the oil decline and FII inflows. The currency had been testing the 95.30 threshold last week, with the RBI's intervention appearing to thin. A sustained crude retreat would ease that pressure significantly.
Analysts cautioned, however, that the decline is contingent on the diplomacy holding. Any breakdown in the Doha talks or a resumption of hostilities would send crude snapping back, and with it the rupee and inflation outlook.
- Brent at $110.37: Down 2.7% on Iran-Qatar diplomacy, offering relief after October's 13.6% surge.
- Rupee at 94.8850: Stronger on oil decline and FII inflows, though still vulnerable to a crude reversal.
- The diplomacy test: A deal to reopen the Strait of Hormuz would be transformative; a breakdown would reverse today's gains instantly.
Sector Story: Oil & Gas, PSU Banks, Metals Lead
The sectoral performance reflected the day's twin drivers. The Nifty Oil & Gas index rose 2.91%, Nifty Infra gained 2.58%, and Nifty Metal climbed 2.17%. PSU Banks also participated, with the Nifty PSU Bank index among the top gainers.
The laggards
Pharma was the notable underperformer, with the Nifty Pharma index trading nearly flat. Sun Pharma fell over 1% despite reporting strong double-digit revenue growth in the September quarter, as one-off expenses related to acquisitions and litigation settlements weighed on profitability.
IT and Financial Services posted modest gains, with the Nifty IT index up just 0.43%. The muted IT performance reflects the ongoing global technology selloff, though Indian IT has been a relative beneficiary as enterprises potentially favor outsourcing over expensive in-house AI investments.
- Oil & Gas up 2.91%: The top sectoral gainer, driven by Reliance and the crude decline.
- Metal up 2.17% and Infra up 2.58%: Broader risk-on sentiment lifted cyclical sectors.
- Pharma flat: Sun Pharma's one-off expenses outweighed revenue growth, keeping the sector subdued.
The FII Return: A Trend or a Blip?
The third pillar of Monday's rally was the continued return of foreign institutional investors. FIIs bought equities worth ₹3,598.54 crore on Friday, extending their buying after a ten-week selling streak. For the week ended October 31, FIIs were net buyers of ₹6,305 crore, their first weekly net purchase in over two months.
The context that matters
October's total FII outflow still stands at ₹45,162 crore, the largest monthly figure since June. The week's reversal is a change in direction, but not yet a change in trend. Whether foreigners continue buying will depend on the trajectory of US yields, the Iran situation, and whether today's crude decline holds.
Domestic institutional investors have been the market's backbone through October, buying ₹62,220 crore and more than offsetting the foreign selling. Their support has been consistent for eleven consecutive weeks, though the pace moderated last week as domestic funds booked profits amid the recovery.
- FII buying of ₹3,598 crore on Friday: Extending the return to buying, but October's total outflow remains ₹45,162 crore.
- DII support at ₹62,220 crore in October: Domestic institutions carried the market while foreigners sold.
- The durability question: Today's rally will be tested by whether FIIs keep buying through the week.
Other Key Developments Today
October auto sales hit records on festive demand. Maruti Suzuki posted its highest-ever monthly sales volume at 2.76 lakh units, while Tata Motors, Hyundai, Mahindra, and JSW MG Motor all reported strong dispatch growth.
Oil PSUs reported combined Q2 profits of ₹30,106 crore, rebounding sharply from losses in the previous quarter on refining margin gains.
Cyclone Murasu has formed over the Bay of Bengal and is expected to strengthen into a severe cyclonic storm, with the IMD monitoring its trajectory southeast of Chennai.
In corporate news, Affle 3i announced its subsidiary will acquire Nasdaq-listed Perion Network for approximately $420 million in an all-cash deal. NCC secured additional orders worth ₹1,862.45 crore in October. Granules India's Hyderabad facility received 11 observations from a USFDA inspection.
What to Watch This Week
The week ahead is heavy with catalysts. The US midterm elections on November 3 will shape the political landscape and potentially the timing of any Iran action. US manufacturing data due later today and non-farm payrolls on Friday will provide fresh signals on the Federal Reserve's December path, with markets pricing a 72% probability of a 25-basis-point hike.
On the domestic front, more Q2 earnings are due, though the heaviest hitters have already reported. The rupee's movement around 94.90 and the trajectory of Brent crude remain the two variables that will determine whether Monday's rally extends or fades.
For Indian investors, today's session offers something rare: a genuine confluence of positives. Reliance delivered. Oil cooled. FIIs bought. But the forces that drove October's selling have not disappeared. They have paused, and the market is betting they stay paused.
Keep Reading: More Insights You Might Like
Comments
No comments yet. Be the first to comment!