Three Global Shocks Reshaping the World Economy: France’s Debt Stress, Hormuz Shipping Risk and AI’s New Interest-Rate Problem
Three very different developments unfolding across Europe, the Middle East and Asia are revealing how dramatically the global economy is changing in 2026.
France is struggling to convince investors that it can control one of Europe’s largest government debt burdens. Middle Eastern crude exports have recovered beyond pre-war levels even while attacks on vessels around the Strait of Hormuz are increasing. And in Japan, the central bank is now openly discussing something that would have sounded unusual only a few years ago: whether the artificial-intelligence investment boom itself is changing financial conditions, inflation and the level at which interest rates should ultimately settle.
Individually, each story matters. Together, they reveal a larger transformation in global finance. Government debt, physical energy infrastructure and AI investment are increasingly influencing the same variables: inflation, borrowing costs, currencies, capital flows and central-bank decisions.
Quick Read: What Is Happening Right Now?
Global markets are dealing with three important but very different sources of uncertainty on October 5, 2026.
- France’s growing fiscal problems are putting pressure on French government bonds and contributing to weakness in the euro.
- Middle East crude exports have climbed above their pre-war average even as attacks on vessels near the Strait of Hormuz create a new shipping and insurance risk.
- The Bank of Japan says the global AI investment boom may be stimulating economies and financial markets strongly enough to influence inflation and long-term interest rates.
Story 1: France’s Debt Problem Is Becoming a European Market Problem
One of the most important developments in European financial markets is taking place in France.
Investors have become increasingly concerned about the country’s large fiscal deficit, rising government debt and political difficulty in implementing spending reductions. Those concerns are showing up directly in France’s government bond market and are also weighing on the euro.
On October 5, the euro fell roughly 0.6% to around $1.1185, reaching its weakest level in approximately 17 months as investors reacted to France’s fiscal difficulties and broader concerns about European government finances.
France Is Trying to Find €54 Billion in Savings
The French government has proposed approximately €54 billion in savings as part of its 2027 budget strategy.
The objective is to reduce France’s budget deficit from approximately 5.4% of gross domestic product in 2026 toward 5% in 2027. The challenge is that many of the measures needed to achieve those savings are politically difficult.
Potential measures include restraints on government spending, public-sector wages, pensions and changes to taxation. Opposition from voters, unions and political parties makes implementation uncertain.
- France is seeking approximately €54 billion in budget savings.
- The government aims to reduce its fiscal deficit from around 5.4% of GDP in 2026.
- Political resistance makes implementation of spending cuts significantly more difficult.
Why France’s €3.5 Trillion Debt Load Matters
France has accumulated roughly €3.5 trillion in government debt, making it one of the largest sovereign debt markets in Europe.
Government borrowing becomes especially important when interest rates rise because older low-cost debt eventually has to be refinanced at newer, higher market rates.
France benefited for years from extremely inexpensive borrowing. As those bonds mature, however, the government increasingly needs to replace them with debt carrying substantially higher interest costs.
The Refinancing Problem Is Only Beginning
France is expected to issue around €340 billion of government debt in 2027 to refinance maturing bonds and finance its budget deficit.
This creates a fundamental financial problem. Even if the country does not dramatically increase its debt, refinancing old bonds at higher yields can cause annual interest expenses to rise.
- France carries approximately €3.5 trillion in government debt.
- The country is expected to issue about €340 billion of bonds in 2027.
- Higher refinancing rates can increase government interest costs even without a major increase in borrowing.
Why Investors Are Demanding More to Lend to France
Government bonds are essentially loans made by investors to governments. When confidence deteriorates, investors demand higher yields as compensation for perceived financial and political risk.
French borrowing costs have therefore become an important market indicator.
The Political Problem Makes the Financial Problem Harder
France is approaching its 2027 presidential election while operating with a politically fragmented parliament. That makes unpopular fiscal reforms significantly harder to approve.
Financial markets therefore have to evaluate two separate questions: whether France knows what needs to be done and whether the political system can actually implement it.
- Investors are increasingly focused on France’s ability to reduce its deficit.
- Political gridlock makes fiscal consolidation harder.
- The approaching 2027 election increases uncertainty surrounding future economic policy.
Why France Can Affect the Entire Eurozone
France is not a small peripheral economy. It is one of the European Union’s largest economies and one of the world’s largest government bond issuers.
A sustained increase in French borrowing costs can therefore influence how investors price government debt elsewhere in Europe.
The Contagion Question
Investors are watching whether France’s problems remain specific to France or begin increasing the risk premium demanded from other highly indebted European governments.
If that happens, Europe could experience tighter financial conditions even without the European Central Bank raising official interest rates.
- Higher French yields can influence pricing across European sovereign bond markets.
- European banks hold significant quantities of government bonds.
- A broader bond-market repricing could raise financing costs for governments, companies and households.
Why the Euro Is Being Pulled Into France’s Fiscal Problem
Currency markets are also reacting.
The euro fell to approximately $1.1185 on October 5, its weakest level in about 17 months, while the U.S. dollar remained firm.
Normally, weaker U.S. employment data might hurt the dollar because it reduces expectations for higher Federal Reserve interest rates. Instead, the dollar remained strong partly because investors were even more concerned about European fiscal conditions.
This Creates an Unusual Currency Setup
Investors have reduced expectations for an immediate Federal Reserve rate increase following weaker U.S. employment figures, yet the dollar remains relatively strong against the euro.
That suggests currency traders are increasingly evaluating sovereign fiscal credibility alongside traditional central-bank policy.
- The euro fell to around $1.1185 on October 5.
- French fiscal concerns are contributing to euro weakness.
- Government debt sustainability is becoming increasingly important for currency markets.
Story 2: Middle East Oil Exports Are Recovering — But Ships Are Becoming Less Safe
An equally unusual situation is developing in the Middle East.
For much of 2026, global markets worried that conflict involving Iran could dramatically reduce energy shipments through the Strait of Hormuz.
Instead, crude exports have recently recovered strongly.
Middle Eastern crude oil exports reached between approximately 19.5 million and 22.5 million barrels per day on several days in late September, according to shipping data reported by Reuters.
By October 1, average exports were approximately 18.5 million barrels per day, slightly above the roughly 18 million-barrel-per-day average recorded before the conflict escalated in February.
This Is Not the Oil Story Markets Expected
Normally, greater geopolitical instability around the Strait of Hormuz would be expected to sharply reduce exports.
Instead, producers and shipping companies have found ways to restore substantial volumes even while the security environment remains extremely dangerous.
- Middle East crude exports recently exceeded their pre-war daily average.
- Daily flows reached approximately 19.5 million to 22.5 million barrels on several days.
- Supply volumes are recovering even though security risks remain unusually high.
The Strait of Hormuz Is Moving More Energy Again
The Strait of Hormuz is one of the most strategically important energy corridors in the world.
Before the latest conflict, roughly one-fifth of global crude oil and LNG supply passed through or was linked to this narrow maritime route connecting Gulf producers with international markets.
Liquefied natural gas traffic linked to Qatar has also begun increasing again, with several QatarEnergy-associated vessels resuming visible movements through the strait.
Energy Trade Is Adapting to War
The recovery demonstrates that global commodity supply chains can sometimes adapt more quickly than expected.
Tankers have adjusted routes and operating practices, producers have used alternative infrastructure and some vessels have reportedly travelled with tracking systems disabled during particularly dangerous periods.
- Crude flows through and around the Gulf have recovered significantly.
- Qatar-linked LNG tanker traffic has also increased.
- Alternative routes and operational changes are helping producers restore exports.
But Tanker Attacks Are Increasing
The recovery in exports hides an important new risk.
At least seven recent maritime incidents have been reported around the Strait of Hormuz and neighbouring waters.
The UK Maritime Trade Operations agency reported attacks occurring daily from October 2, highlighting the continuing danger for commercial vessels.
The Kazimah III Incident Shows the Risk
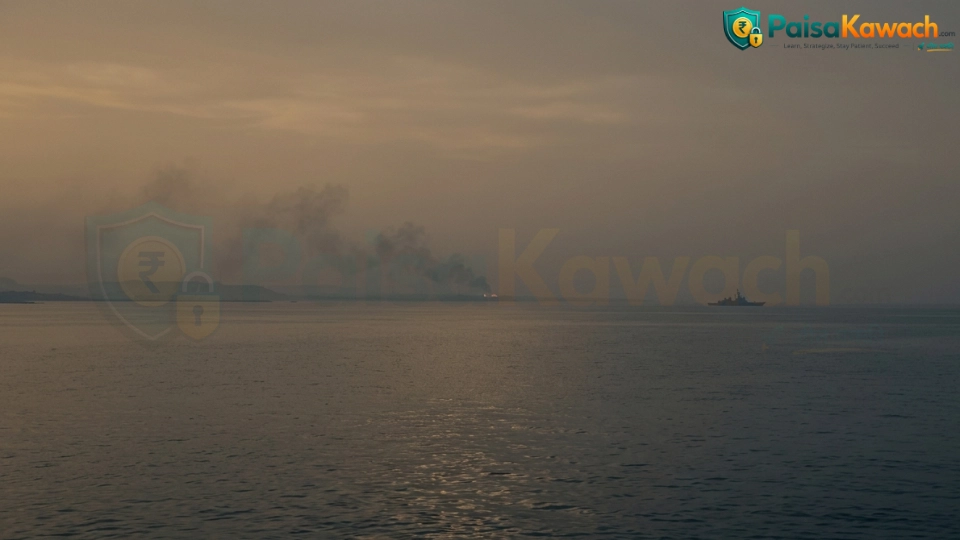
The tanker Kazimah III was struck by an unidentified projectile, causing a fire aboard the vessel.
Maritime-security analysts have suggested that some incidents may involve missiles or other weapons launched into predetermined zones rather than attacks aimed at individually selected commercial ships.
If that interpretation is correct, merchant vessels may face significant danger simply by entering certain maritime areas.
- At least seven recent vessel-related security incidents have been reported.
- Attacks have reportedly occurred daily since October 2.
- Commercial vessels may face risks even when they are not specifically targeted.
The New Energy Risk May Be Shipping Cost, Not Oil Availability
This creates a very different economic problem from a traditional oil shortage.
If crude continues flowing but transporting it becomes significantly more dangerous, the impact may increasingly appear through shipping costs rather than purely through the price of the commodity itself.
Insurance Could Become the Hidden Oil Price
Tankers operating in dangerous waters typically require additional war-risk insurance. Ship owners may also demand higher freight rates to compensate crews and investors for accepting greater risk.
That means the delivered cost of oil could rise even if the underlying crude benchmark does not increase dramatically.
- War-risk insurance premiums can increase when tanker attacks intensify.
- Freight companies may charge higher rates for dangerous routes.
- Consumers can ultimately face higher energy costs even when physical supply remains adequate.
This Creates a New Type of Inflation Risk
Traditionally, economists think about geopolitical energy inflation as a supply problem: fewer barrels reach the market, oil prices rise and inflation follows.
The current situation introduces another mechanism.
Oil may continue reaching customers, but transportation, insurance, security and rerouting costs can increase the total cost of delivering that energy.
Supply Can Recover While Inflation Risk Remains
This distinction is important for central banks.
A recovery in crude exports may reduce headline oil prices, but elevated logistics costs can continue passing through into diesel, aviation, manufacturing and transportation expenses.
- Physical oil availability is improving.
- Transportation risk remains elevated.
- Energy inflation can persist through logistics even without a severe supply shortage.
Story 3: Artificial Intelligence Is Entering Central-Bank Economics
The third development may ultimately have the longest-lasting impact.
The Bank of Japan is now explicitly examining whether the global artificial-intelligence investment boom is changing financial conditions and the broader economy.
Bank of Japan Deputy Governor Shinichi Uchida said the AI boom may have temporarily eased financial conditions by increasing investment demand and boosting asset prices.
AI Is No Longer Just a Stock-Market Theme
For several years, artificial intelligence was primarily discussed through semiconductor companies, software platforms and technology stocks.
That framework is becoming outdated.
The AI buildout increasingly involves enormous physical investments in data centres, semiconductor factories, electricity generation, transmission infrastructure, cooling equipment and networking systems.
- Central banks are beginning to consider AI investment as a macroeconomic force.
- AI spending can stimulate economic demand and asset prices.
- The infrastructure boom may influence inflation, productivity and interest rates.
How AI Can Actually Loosen Financial Conditions
When companies invest hundreds of billions of dollars in AI infrastructure, the effect goes beyond the technology sector.
Construction companies receive orders. Electrical-equipment manufacturers expand production. Energy demand increases. Data-centre developers purchase land. Semiconductor companies build factories. Investors owning related assets become wealthier.
Collectively, these effects can stimulate economic activity.
Higher Asset Prices Can Encourage More Spending
If AI enthusiasm pushes stock markets significantly higher, households and businesses holding those assets may feel wealthier and become more willing to spend or invest.
That can partially offset attempts by central banks to cool economic activity through higher policy rates.
- AI investment directly increases corporate capital expenditure.
- Rising technology valuations can create a wealth effect.
- Strong investment demand can keep economies hotter than central banks expect.
AI Companies Are Also Changing the Bond Market
Another important shift is taking place in corporate finance.
Technology companies are increasingly using bond and equity markets to fund their massive AI infrastructure programmes.
Alphabet, Amazon, Microsoft, Meta and other major technology companies are committing extraordinary amounts of capital to data centres, chips and cloud infrastructure.
AI Spending Is Creating New Demand for Capital
Large corporate bond issuance increases the amount of debt investors are asked to absorb.
The Bank of Japan noted that large-scale bond issuance associated with AI investment may be contributing to upward pressure on long-term interest rates.
This creates a surprising connection: demand for AI computing capacity can eventually influence the borrowing costs of governments, companies and households.
- Technology companies are increasingly tapping capital markets to finance AI expansion.
- Heavy corporate bond issuance can put upward pressure on market yields.
- AI infrastructure financing may therefore influence broader financial conditions.
Could AI Keep Interest Rates Higher for Longer?
This may become one of the most important economic questions of the next decade.
If AI substantially increases productivity, economies could potentially grow faster without generating excessive inflation.
But during the investment phase, massive spending on power plants, data centres, chips, construction and electrical equipment can also increase demand for scarce resources.
The Natural Interest Rate Could Change
Economists use the term “natural rate of interest” to describe the interest rate consistent with an economy operating around its potential without generating excessive inflation or recession.
The Bank of Japan is considering whether AI-driven productivity growth and capital accumulation could eventually influence this equilibrium rate.
- Higher productivity could raise sustainable economic growth.
- Massive capital spending can increase near-term demand and inflation pressure.
- If the economy’s equilibrium interest rate rises, central banks may ultimately keep rates structurally higher than in the pre-AI era.
But There Is Another Risk: What If AI Profits Disappoint?
Central bankers are not only thinking about the upside.
The enormous amount of capital committed to AI assumes that future revenues and productivity gains will eventually justify today's investments and valuations.
If those expectations prove too optimistic, asset prices could correct sharply.
AI Could Move From Economic Stimulus to Financial Shock
A decline in technology valuations could tighten financial conditions by reducing household wealth, making corporate financing more expensive and weakening investor confidence.
Highly leveraged AI infrastructure projects could also become more difficult to finance.
- AI investment currently supports economic activity and financial markets.
- Future profits need to justify enormous infrastructure spending.
- A major valuation correction could reverse the financial stimulus currently associated with AI.
Interactive View: Follow the Money
These three stories can be understood by following how risk moves through the global economy.
France
Political gridlock → difficulty cutting the deficit → investors demand higher bond yields → government refinancing becomes more expensive → euro comes under pressure → borrowing conditions potentially tighten across Europe.
Strait of Hormuz
Regional conflict → tanker security risk → higher insurance and freight costs → higher delivered energy costs → inflation pressure → central banks face a harder policy decision.
Artificial Intelligence
AI demand → massive capital investment → data centres and energy infrastructure expand → corporate borrowing rises → bond supply increases → long-term yields face pressure → central banks reassess the economy’s equilibrium interest rate.
Why These Three Stories Are Actually Connected
At first glance, French government debt, tanker attacks in the Persian Gulf and artificial-intelligence data centres appear to have almost nothing in common.
But financial markets convert all three into the same fundamental variable: the cost of money.
Everything Eventually Reaches Interest Rates
France needs to borrow enormous amounts from investors. Tanker disruption can increase inflation. AI companies require unprecedented capital investment.
Each development can therefore increase pressure on bond markets.
- Government borrowing increases the supply of sovereign bonds.
- Energy disruption increases inflation expectations.
- AI investment increases corporate financing requirements.
The Global Economy May Be Entering a Capital-Scarcity Era
For more than a decade following the global financial crisis, money was extraordinarily cheap.
Interest rates were low, governments could borrow cheaply and technology companies frequently financed expansion primarily from enormous internal cash flows.
The situation in 2026 looks very different.
Governments, AI Companies and Infrastructure Projects Are Competing for the Same Capital
Governments need trillions to refinance debt. Technology companies need hundreds of billions for artificial-intelligence infrastructure. Energy companies need capital for new supply and security. Electricity networks require investment to handle data-centre demand.
All of these borrowers ultimately compete for investors' money.
- Large sovereign borrowing programmes are increasing bond supply.
- AI infrastructure requires unprecedented private-sector investment.
- Energy and electricity infrastructure require additional capital at the same time.
What Could Happen Next?
The next phase will depend on whether these three pressures intensify or begin to ease.
France: Watch Government Bond Yields
If French borrowing costs continue rising relative to German government bonds, markets may interpret that as increasing concern about France’s fiscal credibility.
Middle East: Watch Tanker Incidents, Not Just Brent Crude
Oil prices alone may no longer provide a complete picture of energy risk. Shipping insurance, freight rates and the number of vessel incidents around Hormuz are becoming equally important indicators.
AI: Watch Corporate Debt Issuance
AI capital expenditure and technology-company bond issuance could provide important clues about whether the technology boom is beginning to materially reshape global interest rates.
- French sovereign spreads can reveal whether Europe’s fiscal concerns are expanding.
- Hormuz shipping activity can reveal whether physical energy trade remains resilient.
- AI-related corporate borrowing can reveal how much additional capital the technology buildout requires.
What Does This Mean for India?
Although all three developments are international, India has direct exposure to each of them.
A weaker euro and stronger dollar can affect the rupee and Indian exporters. Rising Middle East shipping costs can increase India's energy import bill. Higher global bond yields can influence foreign capital flows into Indian stocks and bonds.
AI investment also creates opportunities for Indian data centres, power infrastructure, technology services and digital businesses, while simultaneously increasing electricity requirements.
India Is Connected Through Currency, Energy and Capital
- Middle East shipping disruptions can increase India's crude-oil and LNG import costs.
- Higher global yields can influence FII flows and the rupee.
- AI infrastructure investment could create opportunities for Indian power, data-centre and technology companies.
Frequently Asked Questions
Why is France’s debt situation important to global markets?
France is one of Europe's largest economies and sovereign bond issuers. A sustained rise in French borrowing costs can influence European banks, the euro and government borrowing conditions elsewhere in the eurozone.
Is the Strait of Hormuz still disrupting oil supply?
Oil exports from the Middle East have recently recovered substantially and exceeded pre-war averages on some measures. However, security incidents involving tankers remain elevated, meaning shipping and insurance risks continue even as physical supply improves.
Why would AI make interest rates rise?
AI requires enormous investment in data centres, chips, electricity and related infrastructure. Companies increasingly finance part of that investment through bond markets. Strong capital expenditure can stimulate economic demand while large bond issuance may add upward pressure to longer-term yields.
Could AI eventually reduce inflation instead?
Yes. If artificial intelligence significantly improves productivity, companies could produce more goods and services with fewer resources. That could reduce some inflation pressure over the longer term. The difficulty for central banks is determining whether near-term investment demand or long-term productivity gains will dominate.
What is the biggest risk to markets right now?
Rather than one single event, the broader risk is that governments, technology companies and infrastructure projects all require enormous amounts of capital at the same time while geopolitical disruptions keep inflation elevated. That combination could keep long-term borrowing costs structurally higher.
Conclusion: The World’s Biggest Stories Are Converging on the Price of Money
France’s fiscal problems, tanker attacks around the Strait of Hormuz and Japan’s debate over the economic consequences of artificial intelligence appear to belong to completely different categories of news.
In reality, they are increasingly connected.
France shows how large government debt can become a currency and market problem when investors lose confidence in fiscal policy. The Middle East demonstrates how geopolitical risk can raise economic costs even when physical oil supply continues flowing. The AI boom shows how technological investment can become large enough to influence economic demand, bond issuance and potentially the level of interest rates itself.
The defining global financial story of the coming years may therefore not simply be inflation, artificial intelligence or government debt individually.
It may be the growing competition for capital between governments, technology companies, energy infrastructure and the wider economy.
And if that competition continues intensifying, the era of extremely cheap money may be much harder to restore than markets once expected.
Keep Reading: More Insights You Might Like
Comments
No comments yet. Be the first to comment!