Records, Rare Earths, and a Fallen Giant: Why Monday's Rally Tells Three Different Stories at Once
Some trading sessions produce a single headline that explains everything. Monday wasn't one of those sessions — it produced three genuinely significant, entirely unrelated stories, each one worth understanding on its own terms rather than folding into a single simplified narrative. A surprise Arctic security deal sent a handful of obscure mining stocks up over 100% in hours. Wall Street's technology sector climbed to its first record close since June, on hopes tied directly to a conflict thousands of kilometres away. And one of Europe's most storied industrial names quietly fell out of the continent's own blue-chip index, a symbolic moment that says more about Europe's economic trajectory than any single earnings report could. None of these stories caused each other. All three happening on the same day is worth sitting with.
The Arctic Deal Nobody Saw Coming
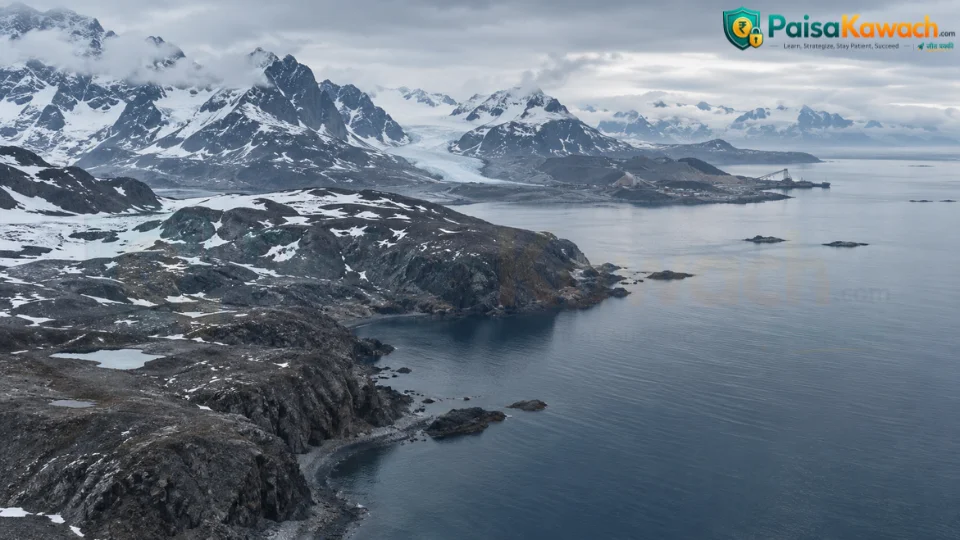
President Trump announced a security agreement regarding Greenland, the world's largest island and a territory that has spent the past year at the center of increasingly serious American strategic interest. The deal, expected to be formally signed during this week's United Nations General Assembly, reportedly involves the United States, Denmark, and Greenland jointly developing a significant military presence on the island — though key operational details remain undisclosed ahead of the formal signing.
The market reaction was immediate and dramatic. Greenland Energy shares soared more than 144% in premarket trading. Greenland Mines jumped nearly 70%. Critical Metals Corp climbed more than 30%. These are not household names, and under ordinary circumstances, a handful of small-cap mining stocks moving this sharply might register as a minor curiosity. What makes this genuinely significant is what these companies are actually positioned to extract: Greenland sits on some of the world's largest untapped reserves of rare earth elements and critical minerals — the exact materials that power everything from electric vehicle batteries to advanced defense systems to the semiconductor supply chains underpinning the global AI buildout.
Why This Deal Matters Beyond a Few Volatile Stock Charts
Rare earth and critical mineral supply chains have become one of the quieter but more consequential battlegrounds in global economic competition over recent years, with China holding a dominant position in processing capacity that has made Western economies genuinely nervous about supply security. A formal US security and development presence in Greenland represents a direct, strategic move to establish an alternative Western-aligned source for exactly these materials — not a speculative mining play, but a geopolitically significant hedge against continued reliance on Chinese-controlled supply chains. The scale of Monday's stock reaction reflects investors recognizing this distinction quickly, even before the formal agreement's specific terms have been made public.
- Greenland holds substantial untapped reserves of rare earth elements and critical minerals essential to EVs, defense systems, and semiconductor manufacturing
- A formal US-Denmark-Greenland security and development pact represents a strategic hedge against China's dominant position in global rare earth processing
- The scale of the stock reaction, well before full deal terms are public, suggests investors are pricing in genuine long-term strategic significance rather than short-term speculation alone
Wall Street's Record Close, Built on Hope for a Different Story Entirely
The second major thread of Monday's session played out on the broader market. The Nasdaq Composite climbed 2.26% to close at 27,122.09 — its first record close since June — while the S&P 500 rose 1.49% to 7,764.70 and the Dow added 366.19 points to 52,048.83. Technology and financial stocks led the advance broadly, while oil and gas shares moved in the opposite direction as crude prices fell.
What's genuinely notable here isn't simply that markets rallied — it's what specifically drove the rally. Improving sentiment ahead of anticipated US-China trade talks combined with renewed hope for diplomatic engagement between the US and Iran at this week's UN General Assembly, alongside a decline in both oil prices and bond yields, provided real relief to investors who have spent much of this year absorbing conflict-driven volatility. This is a market explicitly pricing in the possibility that two of the year's dominant sources of uncertainty — US-China trade friction and the Iran conflict — might both see genuine progress in the same short window.
Why Tying a Stock Record to Diplomatic Hope Is Riskier Than It Looks
Markets rallying on hope rather than confirmed outcomes carries an inherent fragility worth acknowledging directly. This specific conflict has produced multiple cycles of genuine-seeming de-escalation followed by rapid re-escalation over recent months — ceasefires that collapsed within 48 hours, deals that were announced and then quietly walked back through conditional language or fresh military action. A record close built partly on anticipation of diplomatic engagement, rather than a confirmed, durable agreement, carries real downside risk if this week's UN engagement fails to produce the progress markets are currently pricing in. That's not a reason to dismiss Monday's rally, but it is a reason to treat it as provisional rather than settled.
- Monday's record close was driven substantially by anticipation of diplomatic progress rather than a confirmed, finalized agreement on either US-China trade or the Iran conflict
- This conflict's history of rapid de-escalation-to-re-escalation cycles means markets pricing in optimism ahead of confirmed outcomes carry genuine downside risk if this week's UN engagement disappoints
- The simultaneous decline in both oil prices and bond yields reflects a market betting on reduced risk across multiple fronts at once, making the rally more vulnerable to reversal if even one of those fronts fails to deliver
Volkswagen's Fall From Europe's Blue-Chip Index
The third thread carries less immediate market drama but arguably more structural significance. Volkswagen has fallen out of the Euro Stoxx 50, Europe's benchmark blue-chip index — a genuinely symbolic moment for a company that has stood among the continent's most recognizable industrial names for decades. VW shares are down 27.5% this year and currently trade near their lowest level since 2010, a stretch of underperformance severe enough to push the company below the threshold required for continued index inclusion.
This isn't happening in isolation. Earlier this month, Volkswagen approved the next stage of a major restructuring plan that will cut 100,000 jobs, as the company grapples simultaneously with waning profits, intensifying competition from Chinese automakers, ongoing tariff complications, and a genuinely difficult transition toward electric vehicle production that has proven more costly and less immediately profitable than the company's earlier projections assumed.
Why One Company Falling Out of an Index Reflects an Entire Region's Struggle
Index composition changes happen regularly and don't usually carry broader economic meaning — companies rotate in and out of benchmark indices as their relative market value shifts. Volkswagen's specific removal carries more weight because of what the company has historically represented: German industrial strength, European manufacturing competitiveness, and the auto sector's central role in the continent's broader economic identity. A company this symbolically significant falling out of Europe's own flagship index, driven by genuine structural pressures rather than a temporary earnings miss, functions as a concrete, measurable data point confirming what analysts have been warning about more abstractly for months — that Europe's automotive sector, and by extension a meaningful share of its broader industrial base, is facing a genuinely difficult multi-year transition rather than a passing rough patch.
- Volkswagen's removal from the Euro Stoxx 50 reflects a sustained, structural decline rather than a temporary earnings-driven dip, given the stock's 27.5% year-to-date fall to 15-year lows
- The company's approved 100,000-job restructuring plan, combined with Chinese competition and EV transition costs, suggests these pressures are structural rather than cyclical
- Given Volkswagen's historical symbolic weight as a proxy for German and European industrial strength, this development offers a concrete, measurable signal of the sector's broader difficulty rather than an isolated corporate story
Three Threads, One Genuinely Consequential Monday
A speculative rally in Arctic mining stocks, a record close built on diplomatic hope, and a symbolic index departure for one of Europe's most storied companies don't share a cause. But together, they offer a genuinely useful snapshot of where global economic power and risk currently sit. The US is making a concrete, strategic move to secure critical mineral supply chains outside Chinese control. Global markets are betting, provisionally, that two of the year's dominant conflicts might finally see real progress. And Europe's industrial base is confronting structural pressures serious enough to reshape its own flagship benchmark index. Reading all three together offers a more complete picture of this particular Monday than any single headline could on its own — and each thread is worth watching closely as the week's UN General Assembly proceedings unfold.
Keep Reading: More Insights You Might Like
Comments
No comments yet. Be the first to comment!